Can Being an Authorized User Build Your Credit?
6 Min Read | Last updated: August 6, 2026

This article contains general information and is not intended to provide information that is specific to American Express products and services. Similar products and services offered by different companies will have different features and you should always read about product details before acquiring any financial product.
Becoming an authorized user on someone else’s credit card can help establish your credit history. Learn how the primary card member's habits can impact your credit.
At-A-Glance
- Getting added to someone’s credit card account as an authorized user can help you build credit, but only if the primary card member manages their credit responsibly.
- Building a positive credit history requires paying bills on time and keeping your balance low.
- Establishing a healthy credit profile comes from practicing good credit habits over time—not just by being added as an authorized user.
Becoming an authorized user on someone else’s credit card may be a simple way to build your credit with little to no history, but it isn’t an overnight solution. Instead, think of it as an on-ramp to get you started. Building a strong credit profile is ultimately about consistently practicing good credit habits over time.
Let’s break down how being an authorized user works and whether it’s the right move for you.
Do Authorized Users Build Credit?
Being an authorized user can help build your credit. If the primary card member is on top of their game—meaning they have a solid credit score, make on-time payments, and keep their credit utilization low—that can reflect positively on your credit report. Basically, you’re borrowing their good reputation for a bit.
But (and this is a big caveat) it’s not a guarantee. Not all credit card issuers report authorized user activity to the credit bureaus.1 Even when they do, other factors, such as high balances or late payments by the account owner, could hurt rather than help.
What Are the Benefits and Risks of Being an Authorized User?
Here’s a quick look at the perks and potential pitfalls of becoming an authorized user:
| Benefits | Risks |
|---|---|
| You Could Piggyback on Someone Else’s Positive Payment History A well-managed account could give your credit score a boost. |
Their Mistakes Can Become Your Problem If the primary account holder makes late payments, your credit score could take a hit. |
| You Don’t Have to Open Your Own Credit Card It’s a way to start building credit without taking on the responsibility of your own account. |
High Balances Could Hurt Your Credit A high utilization ratio on their account might negatively impact your report. |
| You Can Learn the Ropes Being an authorized user can be a low-pressure way to learn how credit cards work. |
You’re Not in Control You’re relying on someone else’s financial habits. |
| It’s Convenient Some issuers even give you your own card to use. |
It Might Cost You Some issuers charge a credit card fee for adding authorized users.2 |
How Do You Build Credit As an Authorized User?
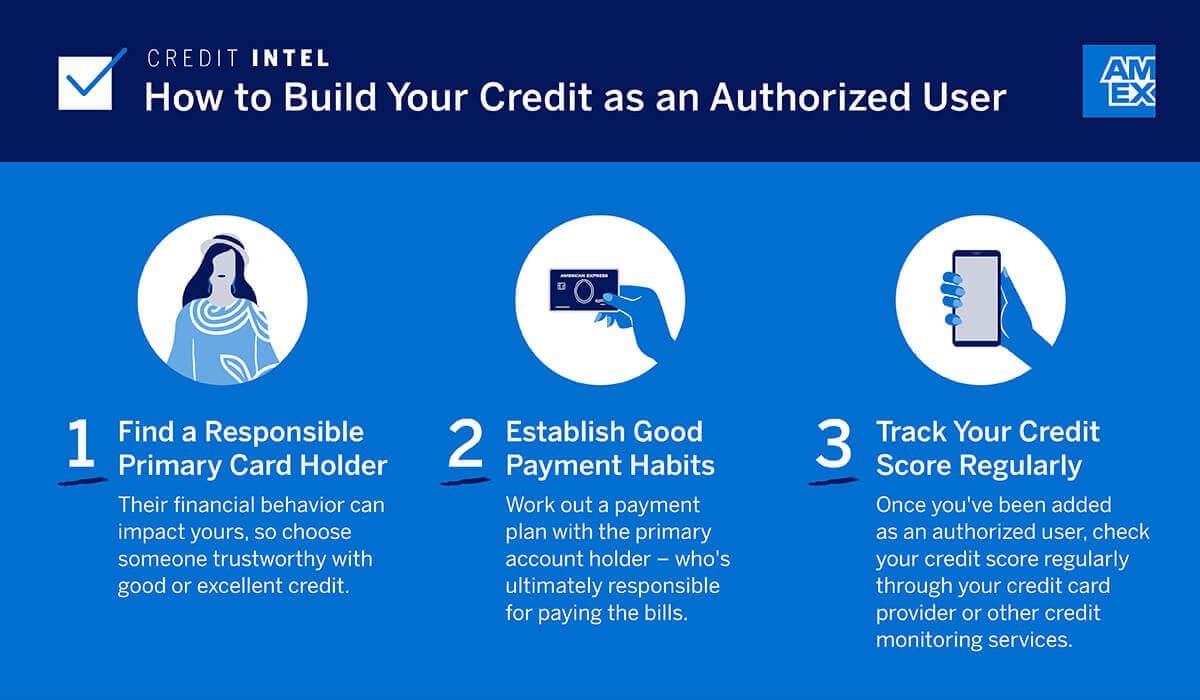
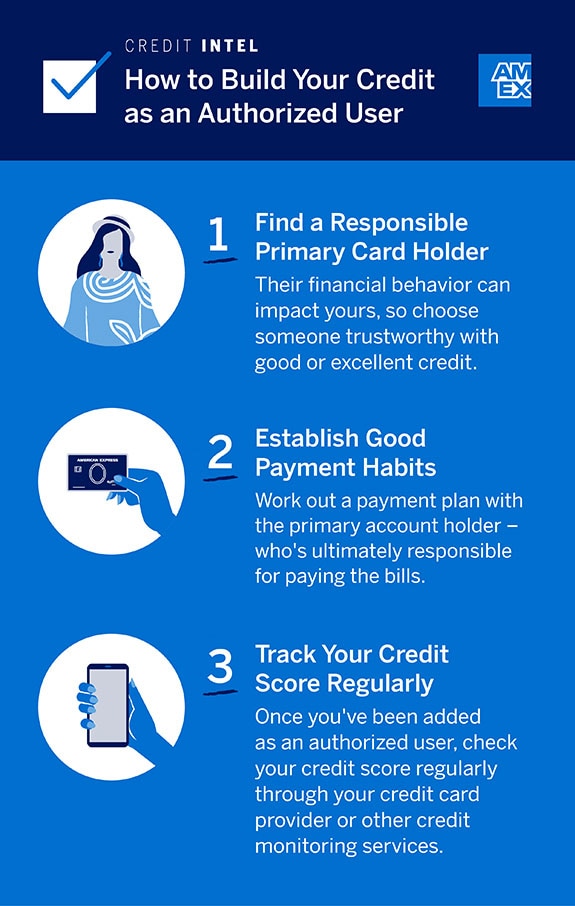
If you decide to become an authorized user, here are a few tips to make the most of it:
- Communicate With the Primary Card Member
Set clear expectations about how each party will use the account and whether you’ll have your own card to make purchases. - Practice Healthy Credit Habits
Even if you’re not responsible for making payments, you can still build good habits, like budgeting and repaying any charges you make promptly. - Check Your Credit Regularly
Keep tabs on how the account is affecting your score by checking your credit report. If being an authorized user is hurting more than helping, consider stepping away.
Staying on top of your credit doesn’t have to be complicated, either. You’re entitled to an annual free credit report from each of the three nationwide credit reporting bureaus. But you also have the option of American Express® MyCredit Guide, a free service that lets you view your FICO® Score and Experian® credit report, as well as helping you build positive credit habits.
Who Should You Ask to Add You as an Authorized User?
Ideally, you should ask someone you trust to add you as an authorized user, like a parent, sibling, or best friend with a strong credit history and good financial habits.
Before you ask, have an honest conversation. Inquire about their payment habits, whether they keep their balances low, and if their credit card issuer reports authorized user activity.
It’s ok to be selective, too. You don’t want to end up in a situation where their financial choices backfire on your credit.
What Are Other Ways to Build Credit?
Being an authorized user is just one way to build credit. You can also try a secured credit card. These cards require a security deposit up front, but they work like standard credit cards. If you use them responsibly, you can build a credit history over time.
Store cards are another option to consider. These are often easier to qualify for and can help you establish credit. Just be sure to pay them off in full each month to avoid potential high interest rates.
Frequently Asked Questions
It typically takes about one to two months for an account to show up on your credit reports after the primary card holder adds you as an authorized user. Once it appears, the credit bureaus will add the account’s payment history and age to your credit history, which will be reflected in your credit scores.3
Your score may have dropped if the account has late payments, a high balance, or other activity that negatively affects your credit profile. A score change may also happen if your overall credit mix, utilization, or account history changes.
You may want to remove yourself from the account if it’s hurting your credit, the primary card member is missing payments, or the balance stays high. You may also decide to stop being an authorized user once you’ve established your own credit accounts and no longer need the account as part of your profile.
The Takeaway
Becoming an authorized user can be a good starting point for building credit, but it’s not a one-and-done solution. Whether it helps or hurts depends on the primary card member’s habits and how the account is managed. If you decide to go this route, choose someone you trust, set clear expectations, and keep an eye on your credit score. And remember, building credit is a marathon, not a sprint—every positive step counts toward the finish line, and there are several effective strategies to build credit and become a savvier credit user.
1 “What Is an Authorized User on a Credit Card?,” Equifax
2,3 “Will Being an Authorized User Help My Credit?,” Experian


Anna Baluch is a personal finance writer from Cleveland, OH. She enjoys helping people from all walks of life make smart financial decisions. Her work can be seen on Credit Karma, Forbes, LendingTree, Insurify, and many other publications. Connect with Anna on LinkedIn.
All Credit Intel content is written by freelance authors and commissioned and paid for by American Express.
Related Articles
How Often Does Your Credit Score Update?
See when, why, and how often credit scores update. Learn how to track your credit score's progress for free and see how much your credit score may change.
How to Check Your Credit Score and Why It Matters
Learn how to check your credit score, why it matters, and what tools you can use to monitor your credit health.
How to Get a Perfect Credit Score
Wondering how to get a perfect credit score? It's possible, but not always feasible. See what impacts your score and what goes into a perfect credit score.
The material made available for you on this website, Credit Intel, is for informational purposes only and intended for U.S. residents and is not intended to provide legal, tax or financial advice. If you have questions, please consult your own professional legal, tax and financial advisors.